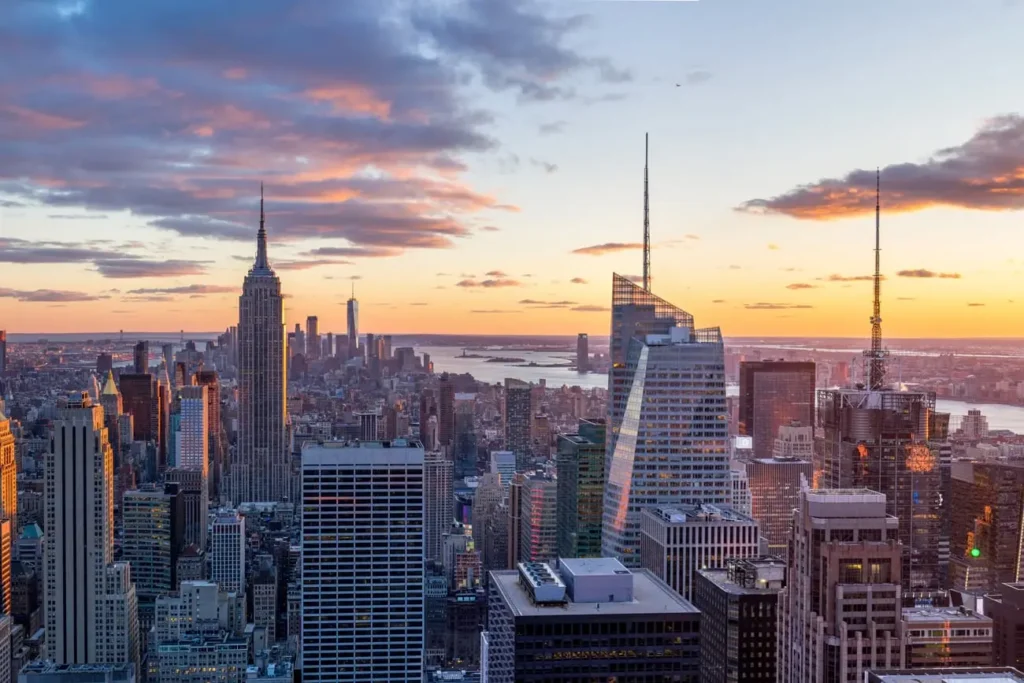
Office Locations / New York City Office
Cresset New York City Family Office & Private Wealth Management
From entrepreneurs to multigenerational families, we guide clients through complex wealth decisions. Speak with a New York City wealth advisor to learn more.
Contact Our New York City Office
By providing your email address, you consent to receive messages from Cresset regarding our services. By providing your mobile phone number and choosing “Text” above, you consent to receive SMS messages (texts) from Cresset regarding information about our services. Message and data rates may apply and you may opt-out by replying “STOP” to any of our messages. View our Privacy Policy.
Meet Our New York City Family Office Team
Meet the NYC-based team dedicated to delivering personalized, boutique wealth management for every stage of life. Whether you are navigating complex estate plans or aligning family values with financial decisions, our team offers personalized support at every stage.
Schedule a call with a New York City advisor to learn more.


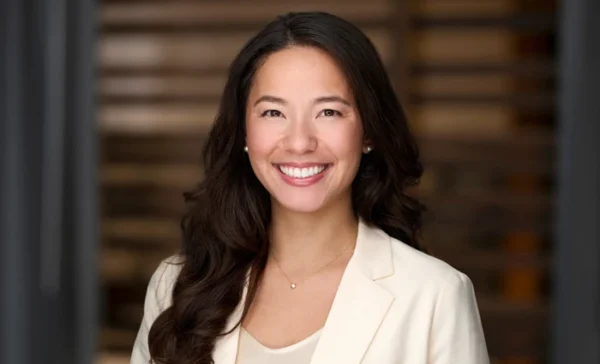
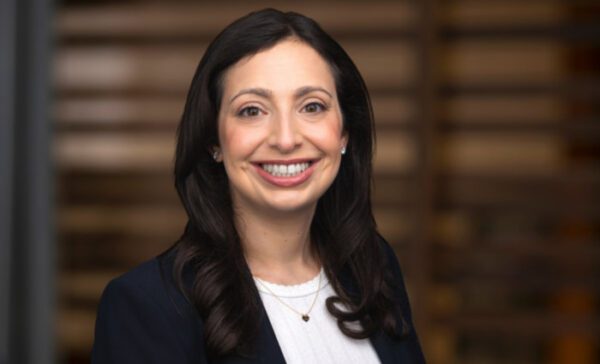
New York City Location
Our Family Office Services in New York City

Cresset’s New York City family office and private wealth management firm serves founders, entrepreneurs, and ultra-high-net-worth families. Our Midtown Manhattan office, just steps from Grand Central Station, supports clients across the New York tri-state area and nationwide through our network of 25+ office locations.
Our New York City location offers a comprehensive suite of services, including investment management, financial planning, exit and liquidity planning, tax strategy, family office services, and more.
As a True Fiduciary®, we are unwavering in our commitment to your best interests—an approach that has earned numerous award recognitions for Top Financial Advisors, Best Multi-Family Office, and Top Advisory Firms.
Partner With a New York City Family Office That Puts You First
Discover how our team can simplify the complexities of wealth so you can focus on what matters most.
$260B+ Family Office
Assets Under Management and Advisement (AUM/AUA) data as of 10/1/26
*Disclosures related to awards, recognitions, and rankings available here.
Barron’s #3 Top 100 RIA Firms
Rankings developed by Barron’s using proprietary algorithms. Awarded 9/11/26 for data as of 6/30/26. Cresset paid a licensing fee to use the Barron’s award logo for marketing purposes.
New York City Office FAQs
What types of clients does Cresset's New York City office serve?
Cresset serves high-net-worth and ultra-high-net-worth individuals and families, including entrepreneurs, founders, business owners, executives, private equity and venture capital partners, professional athletes and entertainers, and multigenerational families. Cresset also provides investment consulting to family offices, foundations, endowments, nonprofits, and other institutions.
What geographic areas does Cresset's New York City office serve?
Cresset serves the entire New York City area including Westchester County and Fairfield County, plus all of New York, New Jersey, Connecticut, and neighboring states. New York City advisors also serve clients in other states throughout the nation and travel to meet with clients.
What's the difference between a family office and a traditional wealth management firm?
Traditional wealth management typically focuses on investment management and financial planning. A family office takes a more comprehensive approach, coordinating the many aspects of significant wealth—including investments, tax and estate planning, trusts, risk management, philanthropy, family governance, and multigenerational wealth planning.
For individuals and families with complex financial lives, a family office can provide a more integrated experience, bringing specialists together to help ensure decisions are coordinated across the family’s entire financial picture.
What is the New York estate tax cliff?
New York’s “estate tax cliff” refers to a provision that can cause an estate to lose the benefit of the state’s estate tax exclusion once its value exceeds a certain threshold.
For 2026, New York’s basic estate tax exclusion is $7.35 million. Once a taxable estate exceeds that amount, the benefit of the exclusion begins to phase out. If the estate exceeds 105% of the exclusion—or $7,717,500 in 2026—the exclusion is eliminated entirely, and New York estate tax is calculated on the full taxable estate rather than simply the amount above the exclusion.
For UHNW New York families, this makes proactive estate, gifting, charitable, and trust planning particularly important. Even relatively small changes in an estate’s value around the threshold can have a significant tax impact.
How does New York decide whether I'm a resident for tax purposes?
New York generally uses two tests: domicile and statutory residency. Your domicile is the place you consider your permanent home—the place you intend to return to. When determining whether someone has changed domicile, New York may consider factors such as the homes they maintain, time spent in each location, business connections, family ties, and where important personal belongings are kept. Simply changing a driver’s license or voter registration may not, by itself, establish a change in domicile.
Even if you are domiciled elsewhere, you can still be treated as a New York resident under the statutory residency rules if you maintain a permanent place of abode in New York for substantially all of the year and spend 184 days or more in the state. Generally, any part of a day counts as a New York day.
For UHNW families with homes and business interests in multiple states, careful residency planning and documentation can be especially important. New York residents are generally taxed on income from all sources, while nonresidents generally pay New York tax only on New York-source income.
What is New York's new pied-à-terre tax, and who pays it?
New York City introduced a new annual surcharge on certain high-value residential properties that are not used as a primary residence, commonly called the pied-à-terre tax. The law took effect in 2026 and applies in addition to regular property taxes.
For the 2026–27 and 2027–28 property tax years, the surcharge may apply to one-, two-, and three-family homes with a New York City Department of Finance market value above $5 million, as well as condominiums and co-ops valued by the Department of Finance at $1 million or more. The applicable rates vary based on property type and value.
The surcharge generally does not apply when the property is used as a primary residence by the owner, a qualifying tenant, an immediate family member, or certain qualifying owners or beneficiaries of an entity or trust.
For UHNW families who maintain multiple residences, the new rules make residency, property ownership structures, and overall tax planning increasingly important when evaluating the cost of maintaining a New York City residence.
Can an irrevocable trust be changed in New York?
Yes, in certain circumstances. Although an irrevocable trust is designed to be difficult to change, New York law provides several potential ways to modify one.
Depending on the trust’s terms and circumstances, options may include obtaining the written consent of the trust creator and all beneficiaries, seeking court approval, or using “decanting,” which allows an authorized trustee to transfer assets from an existing trust into a new trust with different provisions, subject to statutory requirements and limitations.
For UHNW families, these options can be useful when an older trust no longer reflects family circumstances, tax considerations, beneficiary needs, or long-term wealth planning objectives. However, changes must be carefully structured to preserve the trust’s intended legal and tax benefits.